
What Are Emerging Technologies in the Financial Services Industry?
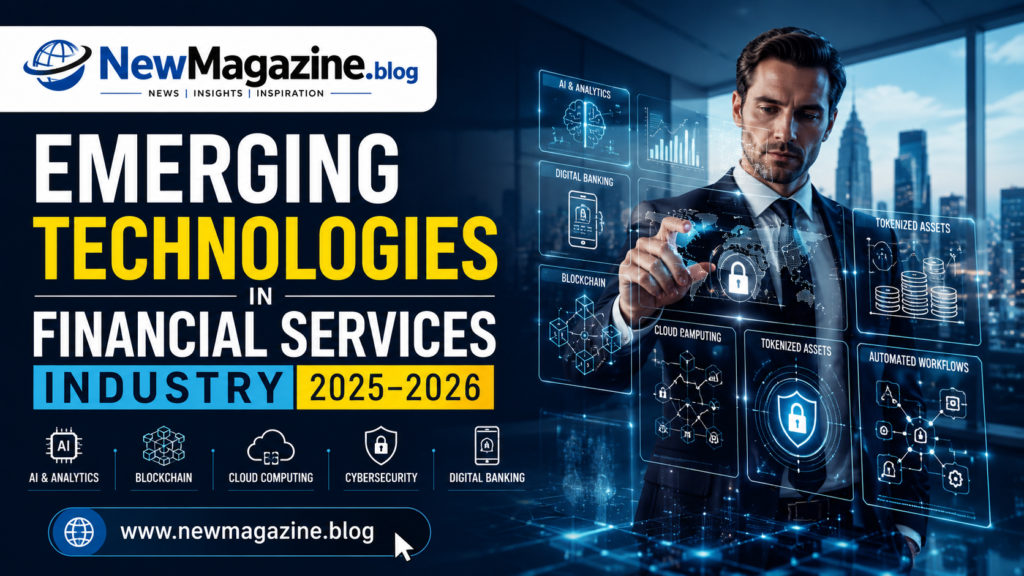
Emerging Technologies in Financial Services Industry are new or rapidly developing digital technologies that can change how financial institutions create, deliver, manage, and secure financial products and services. They include artificial intelligence, machine learning, cloud computing, blockchain, tokenization, advanced analytics, automation, digital identity, cybersecurity technologies, quantum computing, and other innovations. These technologies are being applied across banking, insurance, payments, lending, investment management, wealth management, financial markets, and regulatory operations.
The goal is not simply to replace older systems with newer technology. Increasingly, financial institutions are using technology to make decisions faster, personalize services, automate repetitive processes, improve risk management, reduce fraud, and create new financial products. The transformation is significant because financial institutions operate in a highly data intensive environment. Banks and insurers process enormous volumes of transactions, customer records, market information, documents, and regulatory data. Technologies capable of processing and interpreting this information at scale can therefore create substantial advantages. Deloittes 2026 financial services outlook describes the industry as being influenced by technological disruption, changing customer expectations, regulatory complexity, and competition, with AI and stablecoins among the forces expected to shape financial services.
Why Is Technology Transforming Financial Services?
Technology is changing financial services because customers increasingly expect financial products to be fast, convenient, personalized, secure, and accessible through digital channels. Traditional financial institutions have historically relied on large technology infrastructures and manual processes. While these systems remain important, they can make it difficult to respond quickly to changing customer expectations and competitive pressure from fintech companies and technology platforms.
Customer Expectations Are Changing
Consumers increasingly expect to open accounts, transfer money, apply for credit, manage investments, purchase insurance, and communicate with financial providers through digital interfaces. A customer who can order products, communicate instantly, and receive personalized recommendations from other industries may expect a similar experience from their bank or insurer. This has encouraged financial institutions to invest in mobile applications, cloud platforms, artificial intelligence, APIs, digital identity systems, and automated customer service.
Competition Is Expanding
Competition is no longer limited to traditional banks competing against other banks. Fintech startups, technology companies, payment providers, digital platforms, and embedded finance providers are increasingly participating in financial services. The IMF reported in 2026 that large technology companies are expanding into payments, credit, insurance, asset management, and financial super apps, creating both opportunities and new regulatory considerations. This competitive environment is pushing established financial institutions to modernize their technology infrastructure and rethink how financial products are delivered.
Artificial Intelligence and Machine Learning
Artificial intelligence and machine learning are among the most important emerging technologies in financial services. Financial institutions can use AI to analyze large datasets, identify patterns, detect unusual transactions, support customer service, assess risk, personalize products, and automate decision making. Machine learning models can continuously analyze information and identify relationships that would be difficult to detect manually. The Financial Stability Board has identified applications including risk modeling, trading, fraud detection, financial crime prevention, claims handling, regulatory compliance, and advanced analytics.
AI Powered Risk Management
Risk management is a natural application for AI because financial institutions process huge amounts of structured and unstructured information. AI models can help organizations identify potential credit risks, detect unusual transactions, analyze market conditions, and prioritize cases for human review. However, AI does not eliminate financial risk. Incorrect data, poorly designed models, unexpected market conditions, or insufficient oversight can produce incorrect results.
AI Powered Fraud Detection
Fraud detection is another major application. Traditional fraud systems often rely on predefined rules. AI can complement these systems by examining behavioral patterns and identifying anomalies that may indicate suspicious activity. For example, a system could consider transaction timing, location, device behavior, transaction history, and other signals when assessing whether activity appears unusual.
Generative AI and Agentic AI
Generative AI represents a major development beyond traditional predictive machine learning. Large language models can generate text, summarize documents, analyze information, answer questions, assist employees, and support customer facing applications. Financial institutions are exploring these capabilities for research, documentation, customer service, compliance, software development, and internal knowledge management. The Financial Stability Boards 2026 consultation report emphasizes that financial institutions are increasingly using AI while stressing the importance of governance and controls throughout the AI lifecycle.
Generative AI in Banking
Generative AI can help employees summarize financial documents, draft communications, search internal knowledge bases, explain complex information, and assist with research. For customer service, AI assistants can handle routine questions and direct more complicated requests to human representatives. The important distinction is that financial organizations need to control how AI interacts with sensitive information. Confidential financial data should not be exposed to systems without appropriate security, governance, and data controls.
Agentic AI
Agentic AI goes a step further by allowing AI systems to perform sequences of tasks rather than simply responding to individual prompts. Deloittes 2026 finance technology research highlights the emerging importance of agentic AI and AI native organizations, with finance leaders considering how AI agents can automate routine work and become embedded into business workflows. In financial services, potential applications include workflow automation, research assistance, compliance processes, customer support, reconciliation, and operational decision support. Because these systems can take actions, however, governance becomes even more important.
Big Data and Advanced Analytics
Financial services generate enormous quantities of data. Every payment, withdrawal, loan application, insurance claim, investment transaction, customer interaction, and market movement can generate useful information. Big data technologies allow institutions to store and analyze this information at scale. Advanced analytics can then convert raw data into actionable insights.
Predictive Analytics
Predictive analytics can help financial institutions estimate future outcomes. Banks can use historical information to identify potential credit risks. Insurers can analyze claims patterns. Investment firms can evaluate market information. Financial departments can forecast cash flows and identify unusual changes in expenses or revenue. These capabilities can make decision making more data driven.
Real Time Analytics
Real time analytics is particularly valuable in payments and fraud prevention. Rather than analyzing transactions hours or days after they occur, financial institutions can increasingly evaluate activity while it is happening. This can help organizations respond faster to suspicious transactions, operational problems, and changing customer behavior.
Cloud Computing
Cloud computing is another foundational technology supporting financial transformation. Cloud infrastructure allows organizations to access computing resources, storage, databases, analytics platforms, and applications without maintaining every component on traditional on premises infrastructure.
Scalable Financial Infrastructure
Financial institutions experience variable computing demands. Trading platforms, payment systems, fraud monitoring, customer applications, and analytics workloads may experience significant changes in demand. Cloud infrastructure can provide greater flexibility and scalability when implemented appropriately. Deloittes 2026 finance research shows that finance leaders are increasingly embracing both AI and cloud technologies, with cloud infrastructure playing a significant role in cost management and strategic transformation.
Cloud Security
Moving workloads to the cloud does not automatically make them secure. Financial institutions need strong identity management, encryption, access controls, monitoring, resilience, backup strategies, and third party risk management. Cloud adoption therefore needs to be accompanied by appropriate governance rather than treated simply as an infrastructure upgrade.
Blockchain and Distributed Ledger Technology
Blockchain and distributed ledger technology can change how financial transactions and ownership records are created, verified, and transferred. A distributed ledger allows multiple participants to maintain synchronized records without relying on a single traditional database structure.
Financial Applications of Blockchain
Potential applications include cross border payments, digital assets, securities settlement, identity, trade finance, and tokenization. Blockchain can potentially reduce reconciliation requirements and create programmable financial transactions. However, not every financial problem requires blockchain. Traditional databases can remain faster, simpler, and more practical for many applications. The value depends on whether distributed architecture provides a meaningful advantage.
Tokenization and Digital Assets
Tokenization is becoming an important area of financial innovation. Tokenization involves representing an asset or financial claim digitally on a programmable platform. Depending on the system, this can support more efficient transfer, settlement, recordkeeping, and automation. The Bank for International Settlements said in June 2026 that digital innovation and tokenization could improve payment systems and financial intermediation, while emphasizing the need to preserve trust and manage risks associated with new forms of digital money.
Tokenized Financial Assets
Potentially tokenized assets include securities, funds, deposits, and other financial instruments. Tokenization could enable transactions to be programmed around predefined conditions, potentially reducing settlement friction. However, tokenization introduces questions around legal ownership, custody, interoperability, cybersecurity, liquidity, and regulation.
Stablecoins
Stablecoins are another important development in digital finance. They are designed to maintain relatively stable values compared with highly volatile crypto currencies and may be used for payments or transfers. The BIS has noted that stablecoins demonstrate some potential benefits of programmable payments and tokenization but also have structural weaknesses and potential macro financial implications.
Open Banking and API Technology
Open banking uses APIs and data sharing frameworks to connect financial institutions with authorized third party services. APIs allow different software systems to communicate. This can enable customers to connect financial accounts with budgeting applications, payment services, lending platforms, accounting software, and other financial tools.
Personalized Financial Services
Open banking can give consumers greater control over their financial information where appropriate authorization and regulatory frameworks exist. For example, a personal finance application could aggregate information from multiple financial institutions and provide a consolidated view of accounts and spending. Businesses can also use financial APIs to automate payments, reconciliation, reporting, and account verification.
API Based Banking Infrastructure
APIs are also important for financial institutions themselves. Modern banking ecosystems increasingly depend on integrations between internal systems, fintech partners, payment networks, cloud platforms, identity services, and regulatory systems. Well designed APIs can make these relationships more scalable and flexible.
Embedded Finance
Embedded finance integrates financial products directly into non financial platforms. Instead of visiting a traditional bank website, customers may encounter payment, lending, insurance, or financial management capabilities directly within another digital service.
Embedded Payments
E commerce platforms are a familiar example. Customers can make payments without leaving the merchants digital environment. The same concept can extend to business software, market places, transportation platforms, travel services, and other digital ecosystems.
Embedded Lending and Insurance
Companies can also integrate financing or insurance into their customer journeys. For example, a business platform could offer working capital financing while an online marketplace could provide transaction related insurance. This creates new distribution channels for financial products while potentially making financial services more convenient.
Robotic Process Automation and Intelligent Automation
Robotic process automation, or RPA, uses software robots to perform repetitive digital tasks. Financial institutions often have large volumes of repetitive administrative work involving data entry, reconciliation, reporting, document processing, and account maintenance.
Automating Repetitive Tasks
RPA can reduce manual workload by executing predictable tasks according to predefined rules. This can free employees to focus on activities that require judgment, communication, investigation, and strategic thinking.
Combining RPA With AI
The more interesting development is the combination of RPA with artificial intelligence. AI can interpret documents or identify patterns, while automation systems can execute subsequent workflow steps. This creates what is often called intelligent automation.
RegTech and SupTech
RegTech refers to technology used to help financial institutions meet regulatory requirements. SupTech refers to technology used by supervisory authorities to monitor financial institutions and financial markets. Both are becoming increasingly important as regulatory requirements become more complex and financial institutions generate more data.
Automated Compliance
RegTech can support transaction monitoring, regulatory reporting, identity verification, risk assessment, document analysis, and compliance workflows. Automation can help reduce manual work while improving consistency. However, financial institutions remain responsible for ensuring that automated compliance processes are accurate and appropriately governed.
AI for Financial Supervision
Supervisory authorities can also use AI and advanced analytics to analyze large quantities of financial data. The IMF and FSB have both emphasized the need for stronger oversight and monitoring as AI becomes more deeply integrated into financial systems.
Cybersecurity and Fraud Prevention
Cybersecurity is not simply another technology trend. It is a fundamental requirement for digital financial services. As financial institutions adopt cloud computing, APIs, AI, mobile applications, digital identity, and connected systems, their technology environments become increasingly complex.
AI Driven Cybersecurity
AI can help security teams identify suspicious activity, detect anomalies, prioritize alerts, and accelerate incident response. Deloittes 2026 technology research describes AI powered cybersecurity as an increasingly important way for organizations to detect patterns, respond rapidly, and anticipate evolving threats.
Third Party Technology Risk
One of the most important challenges is dependency. Financial institutions increasingly depend on cloud providers, software vendors, AI model providers, payment networks, and other technology companies. The FSB has warned that concentration among third party AI providers, specialized hardware, cloud infrastructure, and pretrained models can create vulnerabilities. This means technology strategy must include third party risk management.
Biometrics and Digital Identity
Digital identity technologies can make financial onboarding and authentication faster. Biometric technologies may include facial recognition, fingerprints, voice recognition, or other identity signals.
Digital Customer Onboarding
Digital identity can reduce friction during account opening. Instead of requiring customers to visit a branch and provide extensive paperwork, financial institutions can use digital identity verification combined with document verification and other checks. This can make financial services more accessible.
Security and Privacy
Biometric data requires particularly careful handling. Financial institutions must consider consent, data protection, storage security, false matches, spoofing attacks, and accessibility. Convenience should never come at the expense of customer privacy and security.
Internet of Things and Connected Finance
The Internet of Things connects physical devices to digital systems. Although IoT is less visible than AI in financial services, it can create new opportunities. Connected vehicles, smart buildings, wearable devices, retail systems, and industrial equipment can generate information that may support financial products.
Usage Based Insurance
Connected vehicles can provide information about driving behavior. Insurers can potentially use such data to develop usage-based insurance products, subject to applicable privacy and regulatory requirements.
Connected Payments
Connected devices can also support automated payments. Smart devices could initiate transactions based on predefined conditions, potentially creating new forms of machine to machine commerce.
Quantum Computing
Quantum computing is an emerging technology that remains less mature for mainstream financial applications than AI or cloud computing. Quantum computers use fundamentally different computational approaches and could eventually provide advantages for certain highly complex problems.
Potential Financial Applications
Potential applications include portfolio optimization, risk modeling, simulation, cryptography, and complex mathematical problems. However, practical quantum computing for many large scale financial applications remains a developing field. Financial institutions therefore need to distinguish between long term research opportunities and technologies that are ready for immediate deployment.
Post Quantum Security
Quantum computing also creates a cybersecurity concern. Powerful future quantum systems could threaten some existing cryptographic techniques. Financial institutions with long lived sensitive information may therefore need to monitor post quantum cryptography developments and plan migration strategies.
Digital Twins and Financial Simulation
Digital twins are virtual representations of real world systems that can be used to model scenarios. Although better known in manufacturing and engineering, the concept has potential applications in financial services. Financial institutions could use sophisticated simulations to model portfolios, liquidity conditions, operational systems, or business scenarios.
Scenario Planning
Advanced simulation can help financial leaders evaluate how changes in interest rates, market conditions, customer behavior, or operational disruptions might affect the organization. Deloitte’s 2026 finance research highlights advanced scenario planning as an important trend for finance leaders dealing with uncertainty. This makes simulation technologies increasingly relevant to strategic financial planning.
Edge Computing in Financial Services
Edge computing processes data closer to where it is generated instead of sending everything to centralized infrastructure. This can be useful when low latency is critical.
Faster Financial Decisions
Financial markets, payment systems, fraud detection, and connected devices can sometimes benefit from rapid processing. Edge architectures can potentially reduce latency in specific use cases. However, financial institutions must balance performance requirements with security, manageability, and compliance.
Benefits of Emerging Technologies in Financial Services
Emerging technologies can create several major benefits when implemented appropriately. They can reduce operational costs, improve customer experiences, increase processing speed, strengthen fraud detection, support better decisions, and enable entirely new financial products.
Improved Efficiency
Automation and AI can reduce manual processing. Employees can spend less time on repetitive tasks and more time on complex decisions and customer relationships.
Better Customer Experiences
Digital technology can enable faster onboarding, personalized recommendations, instant payments, mobile access, and responsive customer support.
Improved Risk Management
Advanced analytics can help financial institutions identify risks earlier. AI and machine learning can analyze larger datasets and detect patterns that traditional methods might miss.
New Revenue Opportunities
Technology can create new products and distribution channels. Tokenization, embedded finance, AI native banking, digital assets, and personalized financial products may create new revenue opportunities across the financial ecosystem. Deloitte’s 2026 FSI predictions specifically identify AI, digital assets, and changing customer behavior as forces capable of reshaping banking, payments, insurance, investment management, and other financial markets.
Risks and Challenges of Emerging Financial Technology
Technology can create significant value, but financial institutions cannot approach innovation as a purely technical exercise. Financial services operate under strict regulatory, security, privacy, and risk management requirements.
AI Model Risk
AI systems can produce inaccurate or biased outputs. Financial institutions therefore need model validation, monitoring, documentation, human oversight, and appropriate controls. The FSB’s 2026 AI consultation specifically emphasizes responsible AI governance and lifecycle management.
Data Privacy
Financial organizations process highly sensitive customer information. AI, cloud computing, open banking, and connected technologies increase the importance of strong data governance. Organizations must understand where data is stored, who can access it, how it is processed, and how long it is retained.
Cybersecurity
More digital connections create more potential attack surfaces. Financial institutions need layered cybersecurity strategies rather than relying on a single security product.
Regulatory Uncertainty
Technology can develop faster than regulation. This creates challenges for institutions attempting to launch new products while remaining compliant. The IMF’s 2026 analysis of BigTech in financial services highlights regulatory concerns involving data protection, supervision, systemic dependencies, and the expanding role of technology companies.
How Emerging Technologies Are Changing Banking
Banking is one of the industries most affected by emerging financial technology. Digital banking, AI assistants, automated lending, fraud detection, cloud infrastructure, open banking, embedded finance, and tokenization are changing both front-office and back office operations. Traditional branches are increasingly complemented by mobile and digital channels. AI can help personalize customer interactions, while cloud platforms and APIs can make banking infrastructure more flexible. Deloitte’s 2026 outlook identifies AI ambition and stablecoin disruption among major considerations for banks and capital markets.
How Technology Is Changing Insurance
Insurance companies are also adopting emerging technologies. AI can analyze claims, detect potential fraud, assist underwriting, and improve customer service. IoT devices can generate new data sources for usage based insurance.
AI Assisted Claims
AI can help insurers process documents, classify claims, identify anomalies, and prioritize cases. This can potentially reduce processing times while allowing human specialists to focus on complicated claims.
Technology Driven Underwriting
Advanced analytics can provide insurers with additional information for risk assessment. However, insurers must carefully manage fairness, explainability, privacy, and regulatory considerations when using automated models.
How Technology Is Changing Payments
Payments are experiencing rapid technological change. Mobile wallets, instant payments, APIs, digital identity, tokenization, embedded payments, and stablecoins are creating new possibilities. Customers increasingly expect payments to happen almost instantly and with minimal friction. The BIS says digital innovation can improve access to payment services while emphasizing that technological progress must be accompanied by safeguards that maintain trust and financial stability.
How Technology Is Changing Lending
Lending decisions traditionally depend heavily on financial statements, credit histories, income information, and other conventional data. AI and alternative data can potentially expand the information available to lenders.
Automated Credit Assessment
Machine learning can analyze large datasets and identify patterns associated with repayment risk. Automated systems can potentially speed up loan decisions.
Responsible AI Lending
Faster decisions do not automatically mean better decisions. Financial institutions must carefully evaluate models for bias, explainability, accuracy, data quality, and regulatory compliance. This is particularly important because automated credit decisions can directly affect peoples access to financial products.
How Technology Is Changing Investment and Wealth Management
Investment firms are increasingly using technology to process market information, analyze portfolios, support research, automate operations, and personalize client experiences. AI can help analysts process large quantities of information more efficiently.
AI Investment Research
Generative AI can summarize reports, earnings information, research documents, and other textual data. It can act as an analytical assistant rather than necessarily replacing professional investment judgment.
Personalized Wealth Management
Advanced analytics can help financial advisors understand client preferences, financial goals, risk tolerance, and portfolio behavior. This can support more personalized recommendations while keeping human professionals involved in important decisions.
Latest Emerging Technology Trends in Financial Services
The financial technology landscape in 2026 is moving from isolated experimentation toward deeper integration. AI remains the dominant theme, but it is increasingly being combined with cloud infrastructure, cybersecurity, APIs, automation, data platforms, and specialized financial applications.
AI Is Moving Toward Production
Deloitte’s 2026 research indicates that AI adoption in finance is increasingly focused on measurable business impact rather than experimentation alone. This shift means financial institutions are increasingly asking practical questions What problem does the technology solve? What is the return on investment How can it be governed? How can it be integrated into existing infrastructure?
Tokenization Is Gaining Attention
Tokenization is also becoming an important part of the future financial infrastructure discussion. The BIS argues that tokenization can potentially improve payment and financial intermediation processes, although it emphasizes the need to address weaknesses and preserve trust in the monetary system.
BigTech Is Expanding Financial Participation
Large technology companies are increasingly participating in financial services. The IMF’s 2026 analysis identifies payments, credit, insurance, asset management, and financial super apps as areas where BigTech participation is growing. This development could increase competition while also creating new supervisory and systemic considerations.
How Financial Institutions Should Adopt Emerging Technology
The best technology strategy is not necessarily the one that adopts the largest number of technologies. Financial institutions should begin with business problems and then determine which technology can solve them effectively.
Start With Business Value
Organizations should identify high value problems such as fraud losses, slow onboarding, expensive manual processes, poor customer experiences, or inefficient compliance workflows. Technology should then be evaluated against measurable outcomes.
Build Strong Governance
Technology governance should cover security, privacy, model risk, third party dependencies, regulatory compliance, data management, and operational resilience. This is particularly important for AI. The FSB’s 2026 consultation recommends organization wide practices for responsible AI governance across the AI development and deployment lifecycle.
Modernize Infrastructure
Emerging applications cannot reach their full potential when underlying systems are fragmented. Financial institutions may need APIs, modern data platforms, cloud infrastructure, identity systems, cybersecurity controls, and interoperable architecture.
Keep Humans in the Loop
Automation should not remove human judgment from every financial decision. For high impact activities, human review can provide an important safeguard. The objective should be human plus technology, where machines handle scale and repetitive analysis while professionals handle judgment, exceptions, relationships, and accountability.
The Future of Emerging Technologies in Financial Services
The future of financial services will probably not be defined by one technology. Instead, the industry is moving toward combinations of technologies. AI may operate on cloud infrastructure, access information through APIs, analyze data from multiple sources, use digital identity for authentication, trigger automated workflows, and interact with tokenized financial assets. This convergence could produce financial services that are more automated, personalized, real-time, and embedded into everyday digital experiences.
At the same time, the risks will also become more interconnected. The IMF and FSB have emphasized concerns involving AI dependencies, cyber risks, data, model governance, concentration, and potential financial stability implications. The winners will therefore not necessarily be the organizations that adopt technology fastest. They are more likely to be organizations that can innovate quickly while maintaining security, trust, governance, compliance, and resilience.
Stay Connect With Us
Conclusion
The landscape of emerging technologies in the financial services industry is changing rapidly. Artificial intelligence, cloud computing, blockchain, tokenization, advanced analytics, automation, open banking, embedded finance, digital identity, cybersecurity, and other technologies are transforming how financial institutions operate and interact with customers. Among these technologies, AI currently stands out because of its broad range of applications. Banks, insurers, investment firms, and other financial organizations can use AI to improve efficiency, analyze information, detect fraud, personalize services, support employees, and strengthen decision making. At the same time, regulators and international financial organizations are emphasizing responsible adoption because AI can introduce model, cyber, data, governance, concentration, and financial stability risks. Tokenization and digital assets are also becoming increasingly important.
Do Not Miss Our
Frequently Asked Questions
What are the emerging technologies in the financial services industry?
Major emerging technologies include artificial intelligence, machine learning, generative AI, agentic AI, cloud computing, blockchain, tokenization, advanced analytics, open banking APIs, embedded finance, RPA, RegTech, digital identity, cybersecurity, IoT, and quantum computing. The importance of each technology varies depending on the financial institution and its specific business model.
Which technology is having the biggest impact on financial services?
Artificial intelligence is currently one of the most influential emerging technologies in financial services. It is being applied to fraud detection, customer service, risk management, compliance, analytics, research, claims processing, and operational automation. Financial regulators and international organizations are also paying increasing attention to the risks associated with AI adoption.
How is AI used in financial services?
AI can be used for fraud detection, credit risk analysis, financial crime monitoring, customer service, document processing, investment research, claims handling, compliance, personalization, forecasting, and operational automation. Generative AI is increasingly being explored for employee assistance, knowledge management, document analysis, and customer interactions.
Is blockchain important for the future of finance?
Blockchain and distributed ledger technology could play an important role in selected areas such as tokenization, payments, securities settlement, and digital assets. However, blockchain is not automatically the best solution for every financial application. Its value depends on the specific use case, regulatory environment, scalability requirements, and interoperability.
What are the biggest risks of emerging financial technologies?
Major risks include cybersecurity threats, data privacy problems, AI model errors, algorithmic bias, regulatory uncertainty, technology concentration, third party dependencies, operational failures, and financial stability risks. These risks are particularly important because financial institutions increasingly depend on shared technology infrastructure and external providers.
How does cloud computing help financial institutions?
Cloud computing can provide scalable computing resources, storage, analytics capabilities, and application infrastructure. It can help financial institutions modernize technology and respond more flexibly to changing workloads. However, cloud adoption requires strong security, resilience, data governance, and third-party risk management.
What is the role of RegTech in financial services?
RegTech uses technology to support regulatory compliance. Applications can include automated reporting, transaction monitoring, identity verification, document analysis, risk management, and compliance workflows.
What will financial technology look like in the future?
Financial technology is likely to become more AI driven, automated, connected, personalized, and embedded into digital platforms. Technologies such as AI, cloud computing, tokenization, digital identity, APIs, cybersecurity, and automation are likely to increasingly work together rather than operate as isolated systems.