
What Is Varo and How Does Its Digital Banking Model Work?
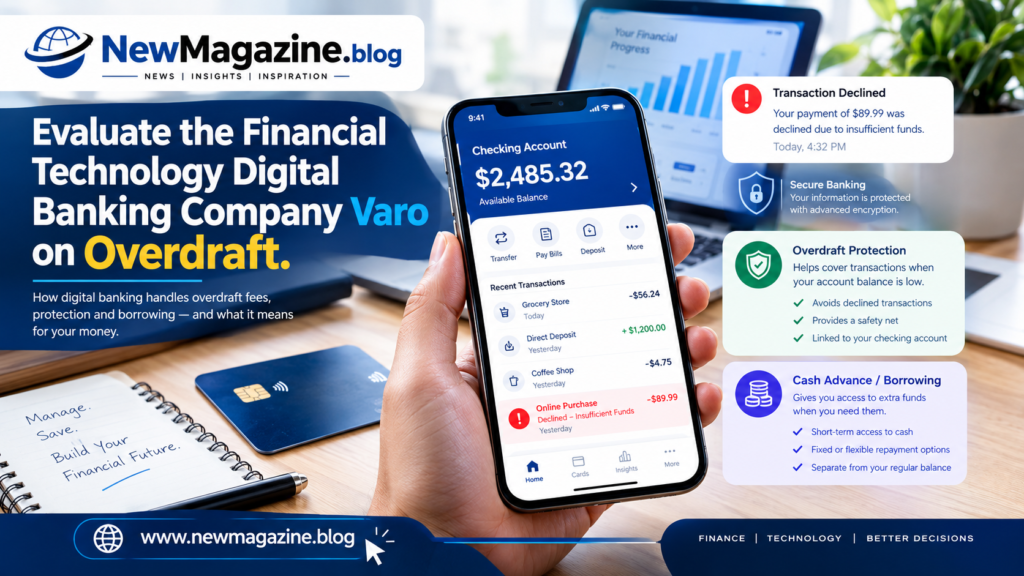
Evaluate the Financial Technology Digital Banking Company Varo on Overdraft, N.A., an FDIC insured national bank. Its banking model is primarily digital, with customers managing their accounts through mobile and online services rather than a traditional branch network. Varo positions its banking products around low fee digital banking, direct deposit, savings, early access to qualifying deposits, and borrowing products. Its current disclosures state that Varo Bank does not charge overdraft fees, while also explaining that transactions can be declined when an account does not contain sufficient funds.
Varo’s Approach to Overdrafts
The most important point when evaluating Varo on overdrafts is that Varo does not operate like a traditional bank that routinely pays an overdrafts and then charges a conventional overdraft fee. Varo’s current disclosures say transactions can be declined when customers do not have sufficient funds. An account could still show a negative balance in certain situations, such as when a transaction is approved for one amount but the final charge is higher. Varo says it will not charge an overdraft fee in that situation. This approach can appeal to consumers who want to avoid surprise overdraft charges. However, customers should not assume that Varo will approve every transaction when their available balance is too low.
Does Varo Charge Overdraft Fees?
Varo currently states that it does not charge overdraft fees. This is one of the clearest advantages of the account for customers who are concerned about traditional overdraft costs. Traditional overdraft arrangements can allow a bank to pay a transaction even when there is insufficient money in an account, with the customer later repaying the amount plus a fee. The Consumer Financial Protection Bureau explains that overdraft protection can involve fees and that banks generally cannot charge fees for one time debit card and ATM overdrafts unless the consumer has opted into that coverage.
What Happens When You Do Not Have Enough Money?
If a Varo customer attempts a transaction without sufficient funds, the transaction can be declined rather than paid through conventional overdraft coverage. This can prevent the account holder from accumulating an overdraft fee. That does not mean insufficient funds have no consequences. A declined payment could cause inconvenience, and a merchant could potentially have its own policies regarding a declined transaction. Customers should therefore distinguish between avoiding an overdraft fee and successfully completing a transaction without sufficient funds. The CFPB similarly advises consumers to understand that declining overdraft coverage generally means debit card transactions can be declined when there is not enough money in the account.
How Varo Advance Differs From Overdraft Protection
Varo Advance is one of the most important products to understand when evaluating Varo’s approach to short-term cash shortages. Varo Advance is not simply an overdraft feature. Varo describes it as a small dollar line of credit that can provide an approved amount of cash deposited into a customers Varo Bank Account. Eligibility is determined using factors including account activity and consumer reports.
What Varo Advance Provides
Current Varo information says initial Advance limits can range from $20 to $250, with customers potentially unlocking higher limits over time, up to $700, when they meet applicable requirements such as bringing qualifying direct deposits to Varo and developing a positive account history. This makes Varo Advance fundamentally different from an automatic overdraft facility. Instead of simply allowing an ordinary transaction to push a checking account below zero, an eligible customer can request an Advance and receive the approved funds. Varo’s support documentation says customers can see their available Advance amount and applicable fee in the Varo app.
Is Varo Advance Free?
No. Varo Advance is not the same thing as a fee free overdraft. Varo currently charges a flat upfront fee for each Advance. Its published information says fees depend on the amount borrowed and the customers qualifying deposit history. Varo states that customers receiving at least $800 in qualifying deposits during the relevant period can receive substantially lower Advance fees.
For example, the current April 2026 Varo Advance agreement shows different fees depending on qualifying deposits. Under the listed fee structure, an eligible $100 Advance can carry a $8 fee for customers meeting the qualifying deposit condition, while customers who do not meet that condition can face a higher $16 fee under the applicable newer fee schedule. This distinction is essential for anyone searching for a Varo overdraft alternative. Varo may not charge an overdraft fee, but its separate borrowing product can still have a fee.
Evaluating Varo’s No Overdraft Fee Policy
Varo’s no overdraft fee approach is one of the strongest reasons a consumer might consider the account. For people who have experienced repeated overdraft charges at traditional banks, knowing that Varo says it will not charge an overdraft fee can make budgeting more predictable. The consumer is less likely to see a conventional overdraft charge simply because a debit transaction exceeds the available balance. However, the policy should not be interpreted as Varo will cover any purchase. The account can decline transactions when sufficient funds are unavailable. Therefore, Varo’s model trades some transaction flexibility for protection from conventional overdraft fees.
The Main Advantage
The biggest advantage is straightforward you do not have to worry about Varo charging a conventional overdraft fee simply because a covered transaction overdraws the account. Varo’s current disclosures explicitly promote no overdraft fees, while explaining that transactions are declined when customers do not have sufficient funds. This can be especially useful for consumers who prioritize predictable account costs.
The Main Disadvantage
The primary disadvantage is that a declined transaction can still create a practical problem. Imagine a customer has $40 available but attempts to make a $55 purchase. A traditional bank with an approved overdraft facility might pay the transaction and charge a fee. Varo’s model may instead decline the transaction. If the purchase is optional, this may not matter. If it is an urgent bill, transportation expense, or essential purchase, the customer may prefer having access to an approved line of credit. That is where Varo Advance can become relevant.
Varo Advance Fees and Costs
Varo Advance uses a flat fee model rather than charging interest on the Advance itself. Varo’s current support information says fees are charged per Advance and depend on the approved amount and deposit history. The April 2026 Varo Advance agreement lists fees for different Advance amounts and explains that qualifying deposits can affect the fee. It also lists a $0 annual fee, $0 late payment fee, and $0 return payment fee under the agreement.
Example of the Fee Structure
The current agreement illustrates the concept clearly. A customer receiving an eligible $50 Advance could pay a $4 fee under the qualifying deposit schedule. A $100 Advance could carry an $8 fee, while a $200 Advance could carry a $16 fee under that same schedule. Customers without the qualifying deposit condition can face higher fees under the applicable schedule. Because Varo can update eligibility and fee structures, consumers should check the actual fee displayed in their Varo app before accepting an Advance. The important lesson is that no overdraft fees does not mean all short term borrowing is free.
How Varo Advance Repayment Works
Repayment is another major factor in evaluating Varo. Varo says customers can choose an automatic repayment date between 15 and 30 days after receiving an Advance, subject to the applicable terms. Customers can also make manual payments before the due date through the Varo app. This provides more flexibility than a product that demands repayment immediately.
What Happens If You Cannot Repay?
Customers should pay close attention to this part of the product. Varo says that if an Advance is not repaid by the final due date, the company can deduct the amount owed from incoming deposits to authorized accounts until the Advance is fully repaid. That means customers should not treat an Advance as extra income. It is borrowed money that must eventually be repaid. Someone who repeatedly uses Advances to cover ordinary expenses may find that future deposits are consumed by repayment, potentially creating another cash flow problem.
Who Is Varo Advance Designed For?
Varo Advance is primarily useful for customers who encounter a temporary cash-flow shortage and qualify for the product. It may be useful when a customer knows that money is coming soon but needs a relatively small amount to cover an immediate expense. The product can provide a faster alternative to some high cost forms of short term borrowing.
Customers Living Paycheck to Paycheck
People who regularly experience gaps between expenses and income may find the product attractive. Varo itself has described Varo Advance as a response to customers living paycheck to paycheck and looking for ways to manage increased living costs without turning to more expensive debt. However, repeated reliance on short term borrowing can become expensive and can make future cash flow more difficult.
Customers With Qualifying Direct Deposits
Deposit history is important. Varo says customers can qualify through qualifying deposits and account activity, and it specifically distinguishes qualifying direct deposits from transfers such as person to person payments and certain other deposits. Customers should therefore not assume that every deposit into the account will count toward eligibility.
Varo Overdraft vs Varo Advance
The difference between the two can be summarized simply. Varo overdraft policy Varo says transactions are declined when there are insufficient funds and says it does not charge overdraft fees. Varo Advance An eligible customer can request a small dollar line of credit, receive funds in the Varo Bank Account, and repay the Advance plus its applicable flat fee. These are separate mechanisms.
Which Option Is Better?
If your primary goal is avoiding overdraft fees, Varo’s no overdraft fee policy is attractive. If your goal is getting access to additional cash, Varo Advance may be more relevant if you qualify. But borrowing should be evaluated based on the total cost and repayment ability rather than simply the fact that there is no traditional overdraft fee.
Varo’s Advantages for Consumers
Varo has several characteristics that make its digital banking model appealing. The most obvious is the no overdraft fee approach. The company also emphasizes digital account management, qualifying early direct deposit access, savings products, and additional borrowing options.
No Traditional Overdraft Fee
This is the strongest advantage for consumers who frequently worry about accidental overdrafts. A customer does not have to budget for a conventional overdraft charge simply because a transaction causes a negative balance under the circumstances described by Varo.
Digital Convenience
Varo’s services are designed around mobile and online banking. Customers can monitor their account, review available Advance offers, and manage repayments digitally. This can be particularly convenient for people who rarely use physical bank branches.
Small Dollar Borrowing Option
Varo Advance provides another potential source of short term funds for qualifying customers. The current product starts with relatively small limits and can increase for customers who establish the required account history and qualifying deposits.
Potential Disadvantages of Varo
No financial product is ideal for every consumer. The biggest limitation of Varo’s overdraft model is that avoiding overdraft fees can mean accepting declined transactions when the available balance is insufficient.
Declined Transactions Can Be Inconvenient
A declined debit card transaction can be frustrating, especially when the purchase is essential. Consumers who want transactions to be automatically covered may prefer a bank that offers a traditional overdraft line or linked account protection.
Varo Advance Is Still Borrowing
A customer should not confuse Varo Advance with free overdraft coverage. The Advance carries a fee, must be repaid, and may affect future eligibility or account circumstances if repayment problems occur. Varo also states that negative repayment history may impact credit.
Eligibility Is Not Guaranteed
Customers cannot simply assume they will receive a particular Advance amount. Varo evaluates account activity and consumer reports, and eligibility requirements apply.
Is Varo Better Than Traditional Banks for Overdrafts?
The answer depends on what the consumer values. For someone whose biggest concern is overdraft fees, Varo can be attractive because its current policy does not charge conventional overdraft fees. For someone who values transaction flexibility, the answer may be different. A traditional bank with an overdraft facility may sometimes approve transactions when funds are insufficient, although that coverage can come with fees or other costs.
Fee Avoidance vs Transaction Flexibility
This is ultimately the central comparison. Varo prioritizes avoiding conventional overdraft fees and may decline transactions when there is not enough money. A traditional bank may provide more flexibility through overdraft protection, but consumers need to understand the associated costs. The CFPB recommends that consumers understand their overdraft options and notes that a line of credit can sometimes be an alternative for covering a short term cash shortage.
Is Varo a Good Choice for Avoiding Overdraft Fees?
For consumers whose primary objective is avoiding overdraft fees, Varo is worth considering. Its current disclosures are clear that the company does not charge overdraft fees, and transactions are generally declined when there are insufficient funds. That policy can provide peace of mind for customers who have previously paid repeated overdraft charges.
When Varo May Make Sense
Varo may make sense for someone who
Wants a digital first banking experience
Wants to avoid traditional overdraft fees
Receives qualifying direct deposits
Is comfortable with transactions being declined when funds are insufficient
Wants access to a potential small dollar Advance if eligible
Can manage repayment responsibly
When Another Bank May Make More Sense
A different financial institution could be preferable for someone who
Needs branch based banking
Frequently requires overdraft coverage
Wants a larger credit line
Needs specific banking products unavailable through Varo
Prefers traditional account structures
The best bank depends on individual cash flow patterns, fees, borrowing needs, and access requirements.
Latest Update on Varo Overdraft and Varo Advance
Varo’s current 2026 disclosures show that its overdraft approach remains centered on no overdraft fees, while Varo Advance has evolved with changing eligibility and fee structures. Varo currently states that initial Advance limits range from $20 to $250 and that customers may unlock higher limits up to $700 over time when they meet applicable requirements. The fee structure has also changed over time. The April 2026 Advance agreement lists different fees based on deposit history, making it especially important to check the current offer in the Varo app rather than relying on older articles or reviews.
Why Older Varo Reviews Can Be Misleading
Online banking products change. A review published several years ago may describe an older Advance limit, older fee schedule, or previous eligibility requirements. For this reason, anyone researching Varo should prioritize current disclosures and the terms shown inside their account. Varo itself says customers can view their current Advance limits and applicable fees in the Varo app.
Consumer Review of Varo’s Overdraft Approach
From a consumer perspective, Varo’s overdraft strategy has a clear strength: simplicity. There is no need to calculate a traditional overdraft fee because Varo does not charge that type of fee under its current policy.
Instead, customers generally need to keep enough money available to complete transactions. The trade off is that Varo may not cover an ordinary purchase when the account balance is too low.
This makes Varo particularly interesting for consumers who prioritize avoiding overdraft fees over transaction flexibility.
Overall Evaluation
For overdraft fee avoidance, Varo receives a strong evaluation. For transaction flexibility, the evaluation is more mixed. For short term borrowing, Varo Advance can be useful for qualifying customers, but its fees and repayment requirements mean it should be treated as credit rather than free overdraft protection. For digital banking convenience, Varo is competitive for consumers who prefer mobile first banking. The best way to evaluate Varo is therefore not simply to ask whether it has overdraft protection. The better question is Do you prefer declined transactions with no overdraft fee, or do you need a separate source of credit to cover temporary shortages?
How to Avoid Cash Shortages With Varo
Customers can reduce the need for overdraft alternatives by monitoring their cash flow closely. Setting up direct deposits, maintaining a buffer in the account, tracking recurring payments, and using account alerts can help prevent unexpected shortages.
Maintain a Cash Buffer
Even a small emergency buffer can reduce the likelihood of a declined transaction. Instead of budgeting down to the last dollar, customers can aim to keep a reserve for unexpected expenses.
Monitor Automatic Payments
Subscriptions, utility payments, insurance premiums, and other recurring transactions can create unexpected timing problems. Customers should know when these payments are scheduled and make sure sufficient funds are available.
Use Borrowing Carefully
If Varo Advance is available, it should be considered only when the customer has a realistic repayment plan. Borrowing to cover an isolated emergency is very different from borrowing every pay period to fund normal living expenses.
Stay Connect With Us
Conclusion
When you evaluate the financial technology digital banking company Varo on overdraft, the key finding is that Varo takes a different approach from traditional overdraft programs. Varo currently says it does not charge overdraft fees. Transactions are generally declined when customers do not have enough money in their account. This can benefit consumers who want predictable banking costs.
However, Varo does not provide unlimited access to extra money. Varo Advance is a separate borrowing product with eligibility requirements, limits, fees, and repayment obligations. Overall, Varo can be a strong option for consumers who prioritize no traditional overdraft fees and digital banking convenience. It may be less suitable for people who need transactions automatically covered when their balance is too low.
Do Not Miss Our
Frequently Asked Questions About Varo and Overdrafts
Does Varo charge overdraft fees?
No. Varo’s current disclosures state that it does not charge overdraft fees. Transactions are generally declined when customers do not have sufficient funds.
Does Varo let your account go negative?
A Varo account can potentially show a negative balance in certain circumstances, such as when a transaction is approved for one amount but the final charge is higher. Varo states that it will not charge an overdraft fee for that situation.
What is Varo Advance?
Varo Advance is a small dollar line of credit offered to qualifying Varo customers. Current initial limits range from $20 to $250, with the possibility of higher limits for eligible customers who meet applicable requirements.
Is Varo Advance the same as overdraft protection?
No. Varo Advance is a separate line of credit. Overdraft refers to transactions involving insufficient account funds, while an Advance is money the customer requests and agrees to repay under separate terms.
How much does Varo Advance cost?
The fee depends on the Advance amount and applicable deposit history. Varo’s current fee information states that customers with $800 or more in qualifying deposits can receive lower fees, while the specific fee available to a customer is displayed in the Varo app.
How long do you have to repay Varo Advance?
Varo says customers can select an automatic repayment date between 15 and 30 days after receiving an Advance, subject to the applicable terms. Manual payments can also be made through the app.
Can Varo Advance affect your credit?
Varo’s current disclosures state that negative repayment history may impact credit. Eligibility is also subject to evaluation of consumer reports and Varo account activity.
Is Varo good for people who frequently overdraft?
Varo can be attractive for consumers who want to avoid traditional overdraft fees. However, if someone frequently lacks enough money to cover essential expenses, repeatedly relying on short term borrowing may not solve the underlying cash flow problem.